What Affects Rates in Anaheim
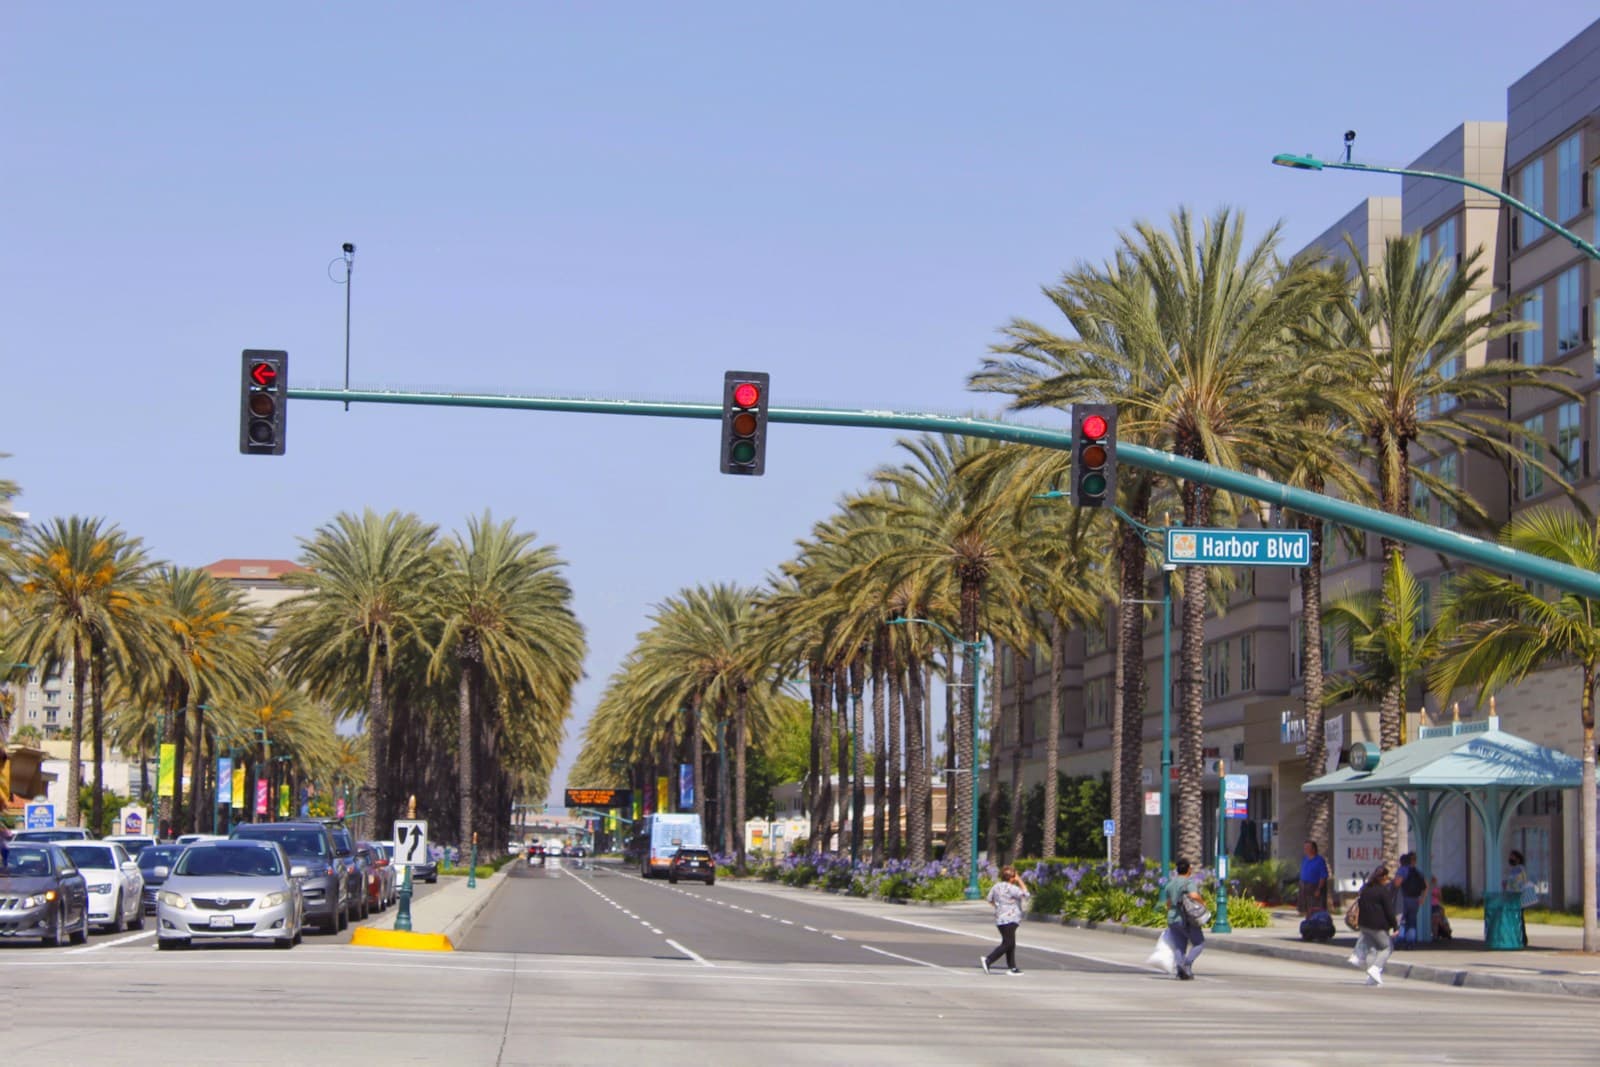
- High Traffic Density on I-5 and SR-91: Anaheim sits at the intersection of I-5 and SR-91, two of California's most congested corridors. Non-standard insurers price violation drivers higher here due to elevated accident frequency in dense traffic — senior drivers with DUIs often see an additional 10–18% surcharge compared to lower-density Orange County suburbs.
- Central Justice Center Case Volume: The Central Justice Center in Santa Ana processes all Anaheim DUI cases, with typical resolution timelines of 45–90 days. Delays in final court disposition postpone license reinstatement and SR-22 filing, extending the period you're uninsured or relying on non-owner policies — costlier for seniors maintaining vehicle ownership.
- Tourist and Convention Traffic Patterns: Anaheim's Disneyland Resort district and convention center generate unpredictable traffic surges year-round. Non-standard carriers factor this congestion into risk models — drivers 65+ with violations face higher premiums in 92802 and 92805 ZIP codes due to elevated collision frequency during peak visitor seasons.
- Uninsured Motorist Rate in North Anaheim: North Anaheim neighborhoods report uninsured motorist rates near 18%, above the Orange County average. For senior drivers already paying non-standard premiums after a DUI, uninsured motorist coverage becomes essential but adds $40–$75/mo to policies — a cost many skip, risking financial exposure.
- Limited Non-Standard Carrier Competition: Anaheim's high-risk market is served by fewer carriers than coastal Orange County markets, reducing competitive pressure on rates. Senior drivers with DUIs often find only 3–5 non-standard insurers willing to quote, leading to premiums 12–20% higher than comparable drivers in Irvine or Costa Mesa.
Compare rates from carriers that specialize in senior drivers
Mature driver discounts, low-mileage rates, and coverage reviews — see what you're actually eligible for.
Get Your Free QuoteCoverage Recommendations
Cost estimates are based on available industry data and vary by driver profile. These are not insurance quotes.
SR-22 Certificate Filing
SR-22 is not a type of insurance — it is a certificate your insurer files with the California DMV proving you carry at least the state minimum liability coverage ($15,000/$30,000/$5,000). Required for three years after license reinstatement following a DUI. Your insurer files electronically; lapses trigger automatic license suspension within 10 days.
$15–$35 filing fee, then $220–$450/mo for underlying non-standard policyEstimated range only. Not a quote.
Liability Insurance
California requires $15,000 per person/$30,000 per accident bodily injury and $5,000 property damage. For senior drivers in Anaheim with a DUI, carrying only state minimums leaves significant financial exposure — accidents on I-5 or Harbor Boulevard often exceed $30,000 in medical claims. Consider 100/300/100 limits if affordable.
State minimum: $180–$320/mo; 100/300/100: $280–$520/mo (65+ with DUI)Estimated range only. Not a quote.
Uninsured Motorist Coverage
Covers your injuries and vehicle damage when hit by an uninsured driver — critical in North Anaheim where uninsured rates approach 18%. Seniors on fixed incomes face financial hardship if hit by an uninsured driver while already paying non-standard premiums. California requires insurers to offer this coverage; you must decline in writing.
$40–$75/mo added to non-standard policyEstimated range only. Not a quote.
Full Coverage (Comprehensive + Collision)
If your vehicle is paid off and valued under $5,000, dropping comprehensive and collision can reduce premiums by $80–$140/mo — meaningful savings for seniors on fixed incomes. If you still owe on the vehicle or it's worth over $8,000, lenders require full coverage and replacement cost justifies the premium.
$120–$240/mo added to liability-only non-standard policyEstimated range only. Not a quote.