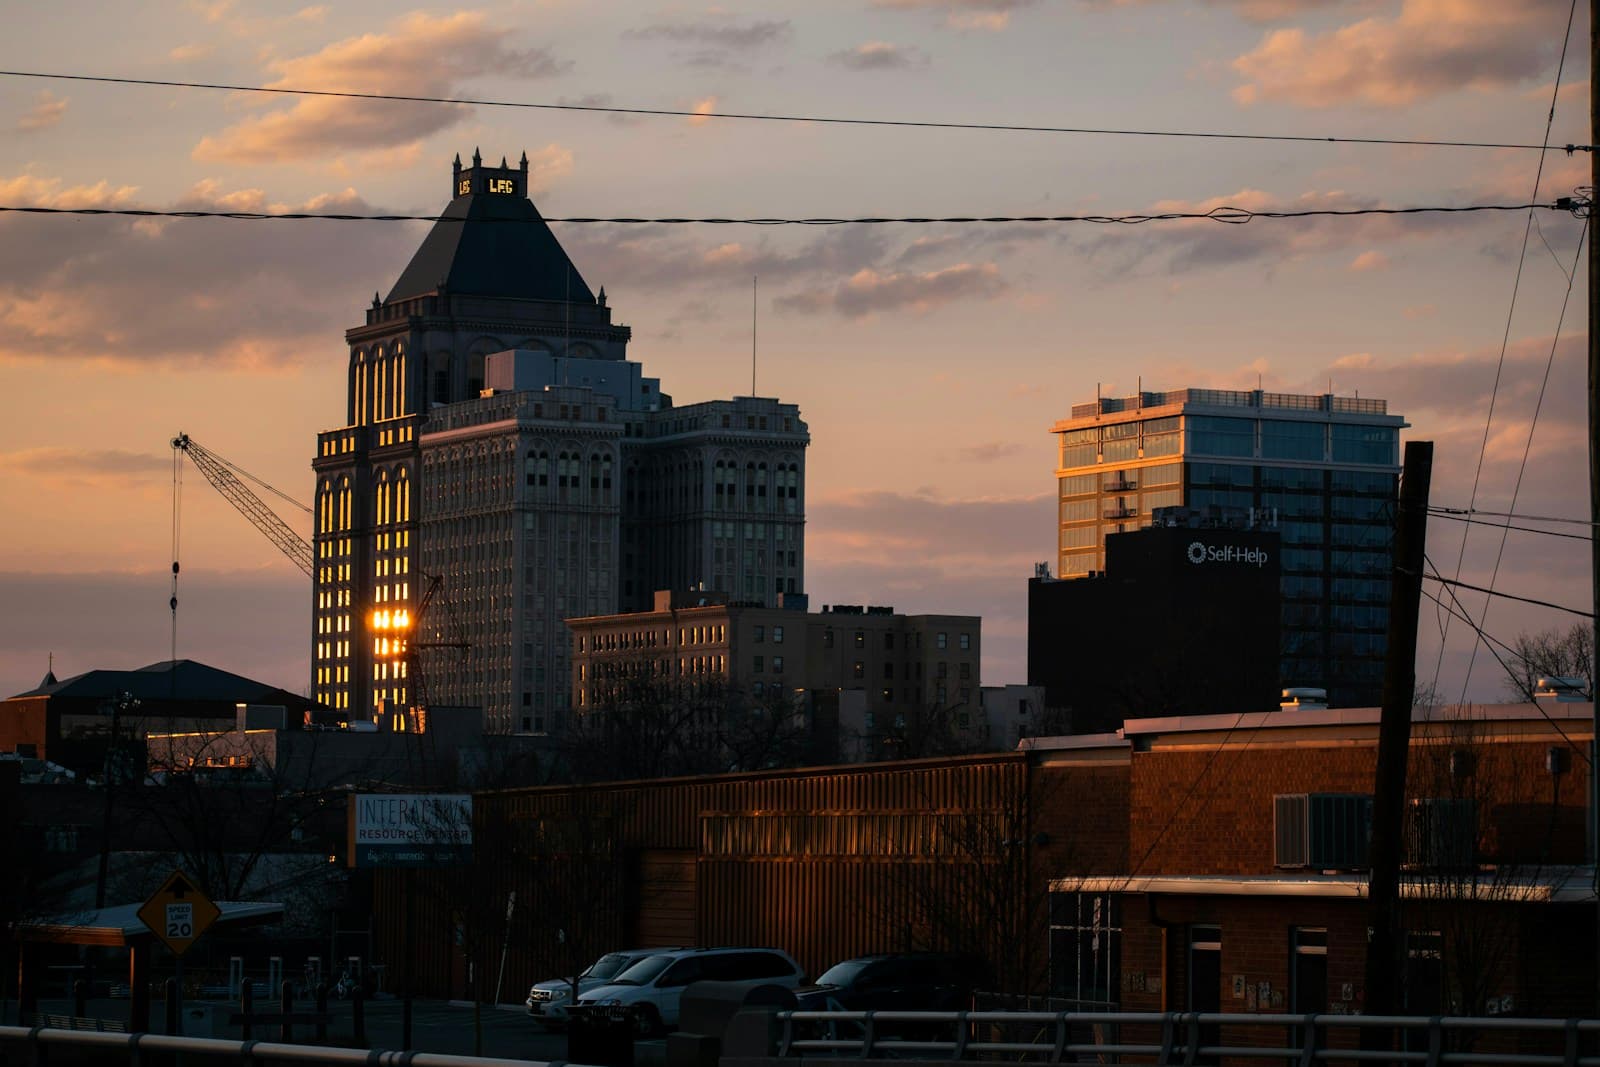
What Affects Rates in Greensboro
- Greensboro's Urban Traffic Density: The concentration of traffic along I-40, I-85, and Wendover Avenue creates higher accident probability, which insurers price into non-standard policies more aggressively than rural North Carolina markets. For drivers already flagged by a DUI, this dense-corridor exposure typically adds 12–18% to premiums compared to less congested counties.
- Guilford County Court Processing and License Reinstatement: After a DUI conviction in Guilford County, the court issues documentation needed for DMV reinstatement, which typically takes 2–4 weeks to process. Your SR-22 filing must be active before the DMV will reinstate your license, so securing coverage immediately after conviction avoids compounding delays.
- Higher-Than-Average Uninsured Motorist Rate: Greensboro's uninsured motorist rate runs approximately 8–10% above the North Carolina average, reflecting economic and demographic patterns in the Triad. This elevates collision risk for all drivers, and insurers price high-risk policies accordingly — often requiring uninsured motorist coverage as a condition of filing SR-22.
- Limited Non-Standard Carrier Competition: Greensboro has fewer local independent agents writing non-standard and high-risk policies than Charlotte or Raleigh, which can narrow your options and reduce rate competition. Drivers age 65+ may find the best rates by contacting regional carriers or brokers specializing in SR-22 filings rather than relying on national brand agents.
Compare rates from carriers that specialize in senior drivers
Mature driver discounts, low-mileage rates, and coverage reviews — see what you're actually eligible for.
Get Your Free QuoteCoverage Recommendations
Cost estimates are based on available industry data and vary by driver profile. These are not insurance quotes.
SR-22 Certificate of Financial Responsibility
SR-22 is not a type of insurance — it is a certificate your insurer files with the North Carolina DMV proving you carry at least the state minimum liability coverage (30/60/25). Most standard carriers will not file SR-22 for DUI drivers, so you will likely need to switch to a non-standard insurer. The filing itself costs $15–$50 one-time, but the underlying policy premium will reflect your violation.
$15–$50 filing feeEstimated range only. Not a quote.
Liability Insurance
North Carolina requires 30/60/25 liability minimums, but drivers age 65+ with assets to protect should consider 100/300/100 or higher limits to shield retirement savings and home equity from lawsuit exposure. After a DUI, you remain legally liable for at-fault accidents, and higher limits often add only $20–$40/month to a non-standard policy.
$80–$180/mo for minimumsEstimated range only. Not a quote.
Uninsured/Underinsured Motorist Coverage
Given Greensboro's above-average uninsured driver rate, UM/UIM coverage protects you and your passengers when an at-fault driver has no insurance or insufficient limits. Many non-standard carriers require UM/UIM as a condition of writing SR-22 policies, and it is particularly important for older drivers who face longer recovery times and higher medical costs after collisions.
$15–$35/moEstimated range only. Not a quote.
Comprehensive and Collision Coverage
If your vehicle is paid off and worth less than $5,000, dropping collision and comprehensive can reduce premiums by 30–40% — meaningful savings when you are already paying high-risk rates. If you still owe on a loan or lease, your lender will require full coverage. Older drivers keeping older vehicles often find liability-only the most cost-effective post-DUI strategy.
$60–$140/mo combinedEstimated range only. Not a quote.